Market Liquidity Basics: Spread, Depth, Cost, and Execution
Updated September 19, 2026
Market liquidity is the ability to trade a stated quantity with limited delay and price impact. It is not simply the number of visible orders or the day's total volume. A useful review combines bid-ask spread, executable depth, cost to trade, trade frequency, order size, and the conditions under which the measurement was taken.
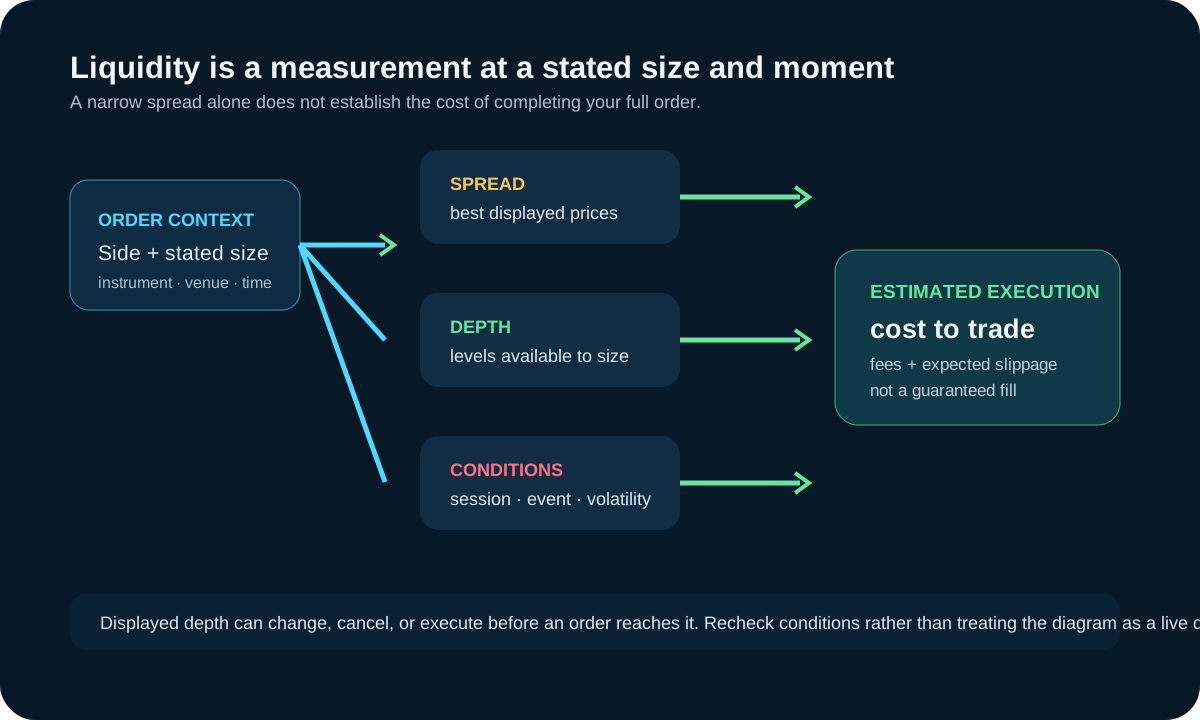
The main liquidity dimensions
| Measure | Question it helps answer | Limitation |
|---|---|---|
| Bid-ask spread | How far apart are the best displayed buy and sell prices? | Does not show how much can trade at those prices. |
| Book depth | How much displayed quantity rests across price levels? | Displayed orders can be changed, canceled, or executed. |
| Cost to trade | How far through the book might a stated order size execute? | Depends on size, side, timestamp, and available levels. |
| Volume and trade rate | How much and how often has trading occurred? | Past transactions do not guarantee future depth. |
Why order size matters
A one-contract order and a much larger order can face different average execution prices. Top-of-book spread alone can therefore understate expected cost. Estimate the full quantity against available levels and include fees, slippage, and the possibility that the book changes before execution.
Executable size, not just displayed size
Displayed depth is an observation of orders resting at recorded levels. It is useful, but it is not a promise that every displayed contract will still be available when an order arrives. Orders can be filled, modified, or canceled; a data feed can aggregate or delay information; and hidden or reserve liquidity may not be visible. Treat the book as evidence about conditions at a time stamp, not as a guarantee of the next fill.
CME's Liquidity Tool illustrates why size belongs in the question: its cost-to-trade measure estimates the cost, in ticks, of buying or selling a fixed lot through available levels. A one-lot estimate and a larger-lot estimate can differ even when the top-of-book spread is the same. The exact methodology and available depth are venue- and product-specific.
Volume is not liquidity
Volume records completed transactions during a period. Liquidity concerns the ability to transact a stated size with limited delay and price impact at a particular moment. A contract can print substantial daily volume yet have a wide spread or shallow book in a quiet time window. Conversely, a short burst of active trading may tighten the visible spread without providing enough depth for a larger order.
Use volume as context, not a substitute for spread, book depth, and estimated cost to trade. The active contract month, venue, session, and intended order size should be part of every liquidity comparison.
Why liquidity changes
Liquidity can vary by contract month, session, scheduled event, volatility regime, holiday, and venue. Lower depth may accompany larger price changes, while rising volatility can also cause liquidity providers to quote less aggressively. The chart alone does not prove which effect came first.
Conditions where a normal reading can fail
Liquidity readings are especially fragile around market opens, major scheduled releases, contract rolls, shortened sessions, and fast price moves. A resting limit order may receive little or no execution when price touches it; a marketable order may consume several levels; and a stop order can be triggered into a changing market. These are mechanics and risk considerations, not predictions about the next price direction.
Compare like with like. A depth snapshot from the most active daytime session cannot safely be used to estimate execution during an overnight or holiday interval. If the platform does not show the same depth, aggregation, or venue as the source being compared, label the limitation rather than assuming the readings are interchangeable.
Example: two orders, one spread
Imagine a market quoted one tick wide. If the intended buy size is completely available at the best offer, the spread describes a useful part of the cost. If only a fraction is available there, the remainder may execute at higher offers, producing a worse average price. The first scenario and the second can share the same quoted spread. The decision-relevant difference is executable depth for the stated quantity.
For a numerical illustration, assume a contract's tick is worth $10 and the best offer shows two contracts at 100.00, with the next three at 100.25. A one-contract marketable buy can be expected to interact with the best offer under the conditions visible then. A four-contract buy may consume both the 100.00 quantity and two contracts at 100.25, producing an average price above the best offer. The exact result can differ because orders may change before execution, but the example shows why a top-of-book quote is not a complete cost estimate.
How to evaluate a live condition
First identify the exact contract, venue, and session. Then state the side and quantity you would actually use. Inspect the spread and the levels needed for that quantity, not only the first level. Check recent trading activity and whether an event, market open, roll, holiday schedule, or platform interruption could make the snapshot unrepresentative. Finally, include commissions and a conservative slippage allowance in the planning number.
If the data source offers a cost-to-trade or market-depth measure, record its methodology and time window before comparing it with a live screen. CME's tool, for example, treats cost to trade as a fixed-lot calculation through order-book levels. A platform's visible depth can use a different feed, aggregation, or refresh behavior. Comparable labels do not necessarily mean comparable measurements.
Limit orders and the false comfort of a price
A limit order sets a worst acceptable price, but it does not promise execution. In a fast or shallow market, price can trade at or through the limit while the order receives a partial fill or none, depending on queue position and market conditions. A market order prioritizes execution but can receive a worse price than the last displayed or last-traded value. Neither instruction removes liquidity risk; each changes which risk is accepted.
This is why a liquidity check should connect to the actual order instruction. A plan that assumes immediate full execution at the best price should be questioned if the displayed quantity is smaller than the intended order or if conditions are changing rapidly.
A practical pre-trade check
- Confirm the exact instrument, active contract, venue, and session.
- Inspect spread and depth for the size you intend to trade.
- Check scheduled releases, exchange notices, and shortened sessions.
- Model slippage beyond the best quote and include commissions.
- Reduce size or stand aside when execution risk exceeds the plan.
After execution, compare the expected and actual average price. If actual slippage repeatedly exceeds the planning allowance, update the assumption rather than treating the difference as bad luck. This process does not predict price direction and does not guarantee a future fill; it makes the cost and uncertainty of transacting explicit.
For related mechanics, see market microstructure and volatility drivers.
Sources, scope, and change risk
Reviewed September 19, 2026 against the following first-party or regulatory sources:
Liquidity is instrument-, venue-, time-, and size-specific. Displayed depth is not guaranteed execution, and stop orders do not guarantee a fill at the stop price. Broker margins and platform displays can change.